The 19 Most Valuable Tax Deductions For Your Small Business

Edgar Vargas

You can’t deduct any of the $15,000 this year by charging expenses to a reserve or liability account. You can deduct your expenses only when you actually pay or accrue them, depending on your accounting method. If you provide your employees with a per diem allowance that covers lodging, meals, and incidental expenses, you must treat an amount equal to the federal M&IE Deductible business expenses rate for the area of travel as an expense for food and beverages. If the per diem allowance you provide is less than the federal per diem rate for the area of travel, you can treat 40% of the per diem allowance as the amount for food and beverages. You can reimburse your employees under an accountable plan based on travel days, miles, or some other fixed allowance.
- Generally, the amount you can deduct for non-entertainment-related meals is subject to a 50% limit, discussed later.
- 100–647, § 3011(b)(3)(B), (C), redesignated subsec.
- Deduct achievement awards, up to the maximum amounts listed earlier, as a nonwage business expense on your return or business schedule.
- If you aren’t sure if the reimbursement or expense allowance arrangement is an accountable or nonaccountable plan, ask your employer.
- However, providing heat and light, cleaning stairways and lobbies, and collecting trash are services normally provided for the occupants’ convenience.
If you want to take the section 179 deduction, you must make the election in the tax year you place the car in service for business or work. Limit on total section 179 deduction, special depreciation allowance, and depreciation deduction. If you and your spouse file separate returns, you are treated as one taxpayer for the dollar limit. You must allocate the dollar limit (after any reduction) between you. You and your employees use your four pickup trucks in your landscaping business.
Complete small business tax deductions list
This exception to the anti-churning rules applies if the person you acquired the intangible from (the transferor) meets both of the following requirements. An individual is considered to own the stock directly or indirectly owned by or for his or her family. Family includes only brothers and sisters, half brothers and half sisters, spouse, ancestors, and lineal descendants. In determining whether an individual directly or indirectly owns any of the outstanding stock of a corporation, the following rules apply.
You receive an allowance only for M&IE when your employer does one of the following. The definition of reasonable period of time depends on the facts and circumstances of your situation. However, regardless of the facts and circumstances of your situation, actions that take place within the times specified in the following list will be treated as taking place within a reasonable period of time. Adequate accounting and returning excess reimbursements are discussed later. Your employer should tell you what method of reimbursement is used and what records you must provide.
Business stage
If both you and your spouse use public transportation, you can only deduct your fare. A bona fide business purpose exists if you can prove a real business purpose for the individual’s presence. Incidental services, such as typing notes or assisting in entertaining customers, aren’t enough to make the expenses deductible.
Here Are the Work Expenses You Can Deduct on Your Tax Return … – CNET
Here Are the Work Expenses You Can Deduct on Your Tax Return ….
Posted: Mon, 17 Apr 2023 07:00:00 GMT [source]
Information that you, as a partner or shareholder, use to figure your depletion deduction on oil and gas properties is reported by the partnership or S corporation on Schedule K-1 (Form 1065) or on Schedule K-1 (Form 1120-S). Deduct oil and gas depletion for your partnership or S corporation interest on Schedule E (Form 1040). The depletion deducted on Schedule E is included in figuring income or loss from rental real estate or royalty properties. The Instructions for Schedule E (Form 1040) explain where to report this income or loss and whether you need to file either of the following forms.
Employees’ Pay
881, which is classified principally to chapter 2B (§ 78a et seq.) of Title 15, Commerce and Trade. For complete classification of this Act to the Code, see section 78a of Title 15 and Tables. 620, which is classified generally to chapter 7 (§ 301 et seq.) of Title 42, The Public Health and Welfare. For complete classification of this Act to the Code, see section 1305 of Title 42 and Tables. This subsection shall not apply to any legislator whose place of residence within the legislative district which he represents is 50 or fewer miles from the capitol building of the State.
The standard mileage rate tends to change a little annually because it’s indexed to inflation. Your business miles must be separated from your personal miles. This can admittedly get complicated, so it’s beneficial to keep a log, either in your smartphone or on a notepad stashed in your glove compartment.
What Can Be Written off as Business Expenses?
If you are a sales representative who calls on customers on an established sales route, you don’t have to give a written explanation of the business purpose for traveling that route. You can satisfy the requirements by recording the length of the delivery route once, the date of each trip at or near the time of the trips, and the total miles you drove the car during the tax year. You could also establish the date of each trip with a receipt, record of delivery, or other documentary evidence. If you used the standard mileage rate for the business use of your car, depreciation was included in that rate. The rate of depreciation that was allowed in the standard mileage rate is shown in the Rate of Depreciation Allowed in Standard Mileage Rate table, later.
Recognized gains must be included in gross income. Recognized losses are deductible from gross income. However, a gain or loss realized from certain exchanges of property is not recognized. Also, you cannot deduct a loss from the disposition of property held for personal use. When preparing a statement of income and expenses (generally, your income tax return), you must use your books and records for a specific interval of time called an accounting period.
Services
File Form 1099-NEC, Nonemployee Compensation, for each person to whom you have paid during the year in the course of your trade or business at least $600 in services (including parts and materials), who is not your employee. The COVID-19 related employee retention credit has expired. An employer that was a recovery startup business could also claim the employee retention credit for wages paid after September 30, 2021, and before January 1, 2022. If you’re an employee, you may have deductible unreimbursed business expenses. A tax deduction lowers your taxable income, which reduces your total amount of taxes owed. That can result in a refund if you overpaid taxes during the year.
Generally, you can use any of the following accounting methods. Only the first $147,000 of your combined wages, tips, and net earnings in 2022 is subject to any combination of the 12.4% social security part of SE tax, social security tax, or the Tier 1 part of railroad retirement tax. You will be asked to complete Form 8879, IRS e-file Signature Authorization, to authorize the provider to enter your self-selected PIN on your return. Many tax professionals can electronically file paperless returns for their clients. You can file most commonly used business forms using IRS e-file. A payee who does not provide you with an identification number may be subject to backup withholding.
Can I take the standard deduction and still deduct business expenses?
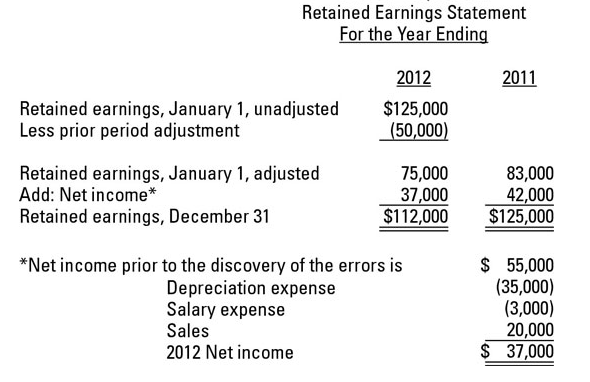
If your deductions for an investment or business activity are more than the income it brings in, you have a loss. There may be limits on how much of the loss you can deduct. If you recover part of an expense in the same tax year in which you would have claimed a deduction, reduce your current year expense by the amount of the recovery. If you have a recovery in a later year, include the recovered amount in income in that year.
In either case, these are just business expenses examples that might be deducted from your taxes. COGS is deducted from an entity’s total revenue to determine gross profit for the year. Any expenses included in COGS cannot be deducted again. Expenses that are included in calculating COGS may include direct labor costs, factory overhead, storage, costs of products, and costs of raw materials. The income statement is the primary financial statement used by businesses to record their expenses and determine their taxes.
- 101–239, title VII, § 7107(a)(2), Dec. 19, 1989, 103 Stat.
- SBDCs provide counseling, training, and technical services to current and prospective small business owners who cannot afford the services of a private consultant.
- He can use the nonfarm optional method and report $6,040 as his net earnings from self-employment.
The 50% limit will apply after determining the amount that would otherwise qualify for a deduction. You first have to determine the amount of meal expenses that would be deductible under the other rules discussed in this publication. The 50% limit also applies to certain meal expenses that aren’t business related. It applies to meal expenses you have for the production of income, including rental or royalty income. It also applies to the cost of meals included in deductible educational expenses. Also assume that the taxpayer and the business contact are not engaged in a trade or business that has any relation to the entertainment activity.
If you rent office space, a warehouse, or any other type of business property, you can qualify as a business expense on your taxes. A rent payment is any amount you pay to use the property for your small business that you do not own. Say you take out a loan for your small business and you pay interest on it. If your taxable income is $100,000 and you paid $60,000 in interest on your loan, you could claim a $30,000 deduction (30% of your taxable income) of that interest as a tax write-off. Before diving into the complete list of small business tax deductions, note these three changes to the list of expenses you can deduct when filing your 2022 taxes.